

I recently shared the stage with Ilana Blumsack from Americans for Prosperity for a discussion about housing in Florida. The Florida Housing Summit is a productive one-day event in St. Petersburg that has recently been hosted annually by former Florida state senator Jeff Brandes’ Florida Policy Project. I recommend the event, if you’re involved in Florida housing policy issues at all. There are great updates about the state of reforms, and St. Petersburg has been a recent success story about the value of thriving residential development in city centers. It is a pleasant place to visit for a couple of days, with a lot of freshly active streets and places to walk to or around.
In the process of putting together my short presentation, I settled upon the 20th century vs. 21st century framing, and I think that framing might extend a few strands of my message marginally a bit further down the road. So, I am going to spend a few posts laying out the points that I laid out in Florida. A lot of this will be a repeat for long-time readers, but I think it will add up to something a little more complete in terms of where the market is and where we should expect it to go.
I think this is useful information for asset allocation and operational decisions; not just for policy discussions. Part 1 is for everyone, but parts 2 & 3 will be for subscribers.
20th Century Housing
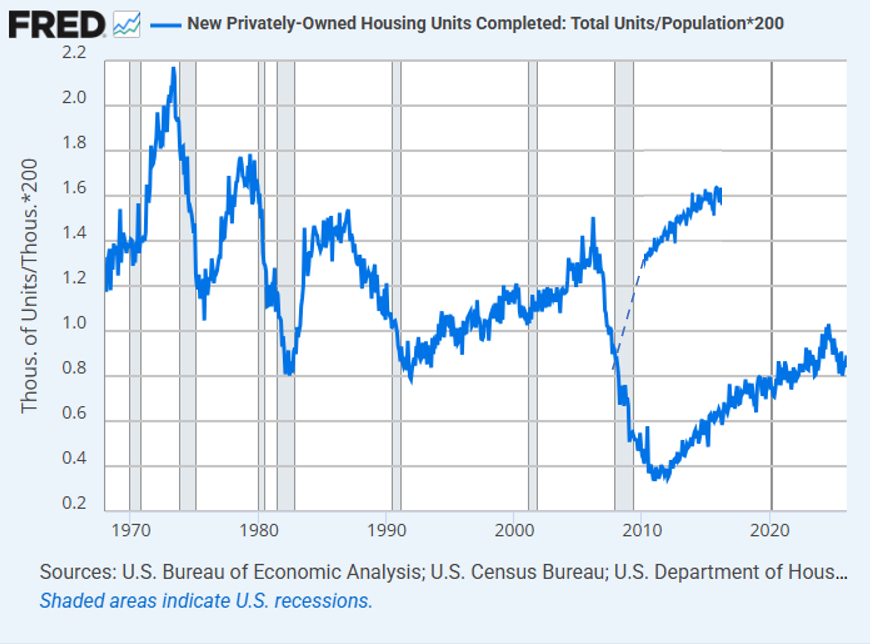
New home construction was highly cyclical in the 20th century. And, almost all of the cyclical volatility was in the form of rising and falling construction activity. When the economy was growing and families were doing well, more households formed, and when recessionary conditions caused families to hunker down, fewer households formed.
In general, households formed when individuals and families wanted them to form, based on current cultural and technological norms, with shifts forward and backward in time across the business cycle.
There were also regional impulses. Sometimes a region would be booming enough that it would attract more population growth than short-term supply channels could handle, and in those cases, regionally, there could be more price volatility.
You could characterize that as “impatience”. There were times when new arrivers didn’t want to wait for local supply channels to catch up, and they would bid local home prices higher while demand temporarily outpaced supply.
That was the main 20th century force creating cyclical price variation - impatience. And, it always corrected back to normal. Eventually, local supply channels caught up to demand. Cycles dependably reverse.
The Cause of the 21st Century Housing Market
As we entered the 21st century, the Closed Access cities deviated from those 20th century norms. In the 20th century, demand outpaced supply, temporarily, in places. By the turn of the century, it outpaced supply permanently in the Closed Access cities (By then, New York, Los Angeles, San Francisco, Boston, and San Diego fit the category.)
Both the public and experts interpreted the trends in those cities through the 20th century lens. When homes get more expensive, it is associated with rising demand, rising construction, and rising home prices. When those are caused by an “impatience” cycle, they always reverse.
But, the Closed Access cities were not in an impatience cycle. This period was associated with stagnating local population growth and rising outmigration. This was permanent, and it was caused by permanently obstructed housing production, not by rising demand. Demand was rising, in the general sense, in that the country, in general, was experiencing normal, non-recessionary economic growth. In 20th century parlance, household formation was at the cycle top, across the country. Demand to live in those particular cities was not rising unusually. They had just clamped down on housing production so thoroughly that regular demand growth outpaces their cap on supply and requires thousands of families to be displaced during cyclical expansions.
Unfortunately, economists viewed these developments through a 20th century lens. Really, it would be expecting a lot, I suppose, to expect anything else. And, when influential economists addressed the Fed, they described the market in 20th century terms. In the 20th century, the only thing that moved prices outside of the normal range were “impatience” cycles. Impatience cycles always corrected.
When Ed Leamer told the Fed in August 2007:
The inevitable effect of those rates (KE: interest rates that he thought were too low before 2006) has been an acceleration of the home building clock, transferring building backward in time from 2006-2008 to 2003-2005. Our Fed thus implicitly made the decision: more in 2003-2005 at the cost of less in 2006-2008. That strikes me as a very risky choice. The historical record strongly suggests that in 2003 and 2004 we poured the foundation for a recession in 2007 or 2008 led by a collapse in housing we are currently experiencing.
he was telling a 20th century story. The Fed had somehow accelerated the pace of household formation, and so, now we were in for a necessary, and large, reversal of an impatience cycle.
Now, there was a lot wrong with this story, even then. Impatience stories are local stories. Impatience cycles in the 20th century had never been associated with extreme national price deviations. That’s why everyone was sharing Case-Shiller price index charts back then. Nationally, the average home prices was roughly 50% elevated. This had never happened before.
And, it is true that there were impatience cycles in Arizona, Nevada, and Florida. But, the impatient buyers weren’t, fundamentally, moving to something. They were moving away from Closed Access markets that refused to approve adequate housing for their existing residents. They were being displaced because of a lack of construction where they were moving away from.
Their displacement led to impatience cycles in Florida, Nevada, and Arizona. The persistently high prices in the Closed Access cities, which represented the bulk of the elevated aggregate real estate value were driven by inertia. Families were willing to pay a lot in an attempt to hold on to what they had, which was becoming increasingly unaffordable. It had to be increasingly unaffordable, because the practical policy of Closed Access cities is to make several hundred thousand of their existing residents miserable enough to give up each year.
Even in the national numbers, Figure 1 does not signal a 20th century cycle story. In 20th century cycles, construction was very volatile. There was nothing of the sort going on before 2008. New home completions were rising regularly, and quite slowly.
As that completions chart continues its post-2008 path into the future, the idea that the little bump in completions around 2004 was a generation defining glut of housing that required massive economic dislocation to correct from is the definition of ludicrous.
Even more ludicrous, 20 years later, there are Federal Reserve economists arguing that local supply conditions aren’t an important source of inflated housing costs because, “we show that for the supply-centric view this correlation (KE: between supply conditions and prices) actually points to implausibly large, ad hoc shifts in housing supply functions.”
I think Erdmann Housing Tracker readers are very smart. I think, if you look at Figure 1, you might be able to locate implausibly large, ad hoc shifts in housing supply functions that are shared across cities after 2008. I know it’s hard. Try squinting if you can’t see it at first. I know you can do it.
In the academy, the bump in 2004 defined a generation and the collapse after that doesn’t exist. Its existence is implausibly large.
If not for the mortgage crackdown in 2008, completions would have looked something like the alternative path I pasted into Figure 1. Even with the Fed’s errors, construction would have recovered, and I suspect we would have spent the subsequent 2 decades with a chart that would have looked like something between the 1970s and 1980s volatile period and the 1990s more cyclically moderate period.
As it happened, the mortgage crackdown pushed us into a permanent condition of undersupply, and so, really, new home completions have been following a uniform, slightly upward sloped trend because of the engineered shortage as we slowly recover from the 2008 shock to mortgage funding (in a context where cities, nearly universally, choose to economically stress their existing residents instead of permitting new infill and multi-unit housing).
As I told the audience in Florida, in the 20th century, in an given year maybe 1 million households wanted to form, or maybe 2 million households wanted to form, and builders built to match that volatile demand.
Today, more than 10 million households always want to form (plus 5 million vacancies that would accompany those 10 million occupied units if the market normalized). So, who cares if 2 million, or 1 million, or even 500,000 households want to form this year. The difference between 15.5 million and 17 million is unimportant. We aren’t going to come close to meeting that demand.
So, the 21st century housing market is very different than the 20th century market was. In short, now, prices are volatile instead of completions. That was already the case before 2008, in the Closed Access cities. Now, we have engineered a housing shortage in almost every city, and so every city has a market that looks more like the Closed Access cities already looked. Housing costs are elevated now in those cities because families are trying to hold on. On top of that, there are still impatience cycles. In the 20th century, you could treat housing entirely as an impatience cycle. Today you can’t. And, they lead to very different patterns in household behavior, rents, prices, and homebuilder activity.
Really, you could describe the permabear case (prices and new home sales are always a year away from repeating 2008 again) as broadly simply a case of this error. They are analyzing the market through a 20th century lens. They are correct that cycles always reverse. They really do! They just haven’t updated their understanding to realize that cycles aren’t the only game in town any more.
It’s easy to see how they would find their point of view to be sincerely self-evident, and that they would find themselves disappointed, year after year, as the impatience cycle refuses to correct. And, how they would find an audience, who also have a point of view that was self-evidently true for a century, eager to pay for and consume their analysis.
Part 2 will be about what the journey from 20th to 21st housing looked like.
Unrelatedly, I wanted to point something out to you: the mortgage crackdown may have been the worst recent occurrence of such, but it’s far from the only.
It was preceded by similar financial regulatory depredations, chiefly on condo liabilities after various high profile failures, and also a slow-burn extinction of financing for the sorts of nonstandard construction that used to constitute most of what we now call missing middle.
For instance, if I owned a duplex and wanted to finance an additional residential unit, keep my primary residence, AND convert the downstairs into a commercial space, even if there were no zoning prohibitions I’d immediately run up against a thicket of financial regulations. Barely any banks would care to even ATTEMPT to underwrite me; even if they could do it correctly and mitigate any extra inherent risk from being a nonstandardized market segment, it’s too much work. It’s cheaper to finance 5-over-1’s, SFH sales, HELOCs and cash-out refis, and other bog-standard paper that Wall Street is built on.
That stuff didn’t disappear in 2009-2011, it had already been gone for decades, and was simply being masked by the sheer volume of SFH construction that had gone on up to 2008. Missing middle was zoned out, and the financial system for it atrophied until it was killed off by regulations meant to streamline SFH.
Just some food for thought.